Do Not Let Anyone Remove the Thing That Started It
This gets almost no coverage anywhere and it can be worth your entire deductible.
If the fire began with an appliance, a heater, a battery, an extension lead or a piece of wiring, that object is evidence. Your insurer will investigate cause and origin, and if the fire is traced to a defective product, the insurer can pursue the manufacturer to recover what it paid. That recovery process is called subrogation, and when it succeeds your deductible is usually returned to you as part of it.
The evidence has to survive for that to happen. Cleanup crews and well-meaning relatives clear debris quickly, and the charred remains of a space heater look like rubbish to everyone except a fire investigator.
So: photograph the suspected source in place, tell the insurer immediately that you want it preserved, and do not allow it to be discarded until you have written confirmation that it has been examined or released. The same applies to the panel board, the wiring at the origin point, and any product packaging or receipts you still have.
The First Twelve Hours
Two things matter and both are short.
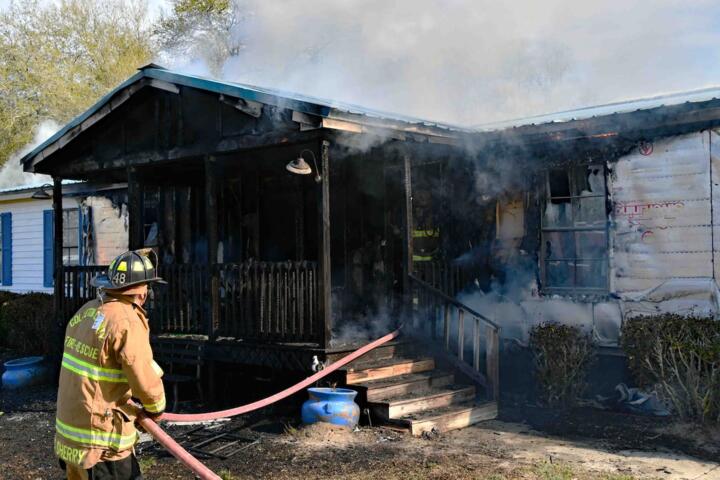
Do not re-enter until the fire service says the structure is safe. Framing can be charred internally while looking intact, and floors above a burned space are the usual failure point. This is not caution for its own sake; people are injured re-entering more often than during the fire.
Report the claim and secure the building. Your policy imposes a duty to protect the property from further damage, and failing it converts covered damage into excluded damage. Boarding openings and covering roof breaches is the visible part; the invisible part is that theft from unsecured fire-damaged houses is common, and the resulting loss may be argued over.
Emergency board-up is reimbursable. Keep every receipt, and photograph the work when it is done. The broader sequencing of the claim is set out in the order to handle your insurance steps after a fire; the rest of this article deals with what is specific to fire and easy to get wrong.
What Speed Actually Buys, and Who Is Telling You
You will read that acting within 48 hours cuts restoration costs by a large percentage. Those figures come from restoration contractors, they are not sourced to any published study, and urgency is what they sell. Treat them accordingly.
The underlying chemistry is nevertheless real, and it is worth understanding on its own terms rather than as a sales argument.
- Soot is acidic. On chrome, brass, marble and stainless steel it begins etching quickly, and the damage is permanent once it has bitten in.
- Firefighting water stays. A structure can hold thousands of gallons in subfloors and cavities, and warm damp cavities grow mold in a matter of days.
- Smoke travels further than fire. Combustion particles are small enough to enter wall cavities, insulation and ductwork in rooms the flames never reached. Those rooms are damaged, and the damage is covered.
Three practical consequences. Do not run the heating or air conditioning, because it distributes contamination through the whole house. Do not vacuum soot with a domestic machine, which drives oily particles deeper into fabric. And do not clean surfaces for appearance before they are documented, because cleaning removes evidence of extent.
The Packout Is Where Your Contents Claim Gets Written
On any substantial fire, a contents restoration vendor will propose a packout: your belongings are inventoried, boxed, moved to a climate-controlled facility, cleaned where possible, stored, and returned when the house is habitable.
It is usually the right decision. It is also the moment your contents claim is effectively drafted, by someone who does not work for you, and most homeowners do not realize that is what is happening.
The vendor's inventory records what was taken, what is salvageable and what is not. The non-salvageable list becomes the contents claim. Four things follow.
- Review the inventory before it is finalized. Descriptions like ""lamp"" or ""jacket"" price generically. Brand, model and material are what determine the replacement figure — the mechanism is explained in proving value on a claim.
- Get your own copy at the time, not months later. You cannot check a list you have never seen against a house you can no longer enter.
- Ask who decides salvageability and on what basis. Restoring an item generates revenue for the vendor; so does replacing it. Neither incentive necessarily aligns with yours, and items with sentimental rather than monetary value are the ones most often written off.
- Watch the storage clock. Storage is billed monthly, and on a rebuild that runs long the charges can consume a meaningful share of your contents limit or your additional living expenses, depending on how your policy allocates them. Ask which it is at the start.
Before any of it leaves, walk through with a camera if you are permitted to. A household that photographed its own rooms before the packout has a reference point; one that did not is dependent on someone else's list.
Six Coverages That Apply and Get Missed
| Coverage | What it does after a fire |
|---|---|
| Additional living expenses | Pays the increase in your cost of living while the home is uninhabitable. Smoke odor and loss of utilities can make a house uninhabitable without visible structural damage — see what it pays for |
| Debris removal | Usually a separate allowance, often expressed as a percentage of the dwelling limit. Fire debris is heavy and disposal is regulated |
| Fire department service charge | A small stated limit covering charges levied by the responding service, which apply in some districts |
| Ordinance or law | Funds the gap between replacing what was there and meeting a building code adopted since. On a substantial fire this is frequently the largest single omission from a settlement |
| Trees, shrubs and other structures | Detached garages, fences and landscaping carry their own limits, and fires reach them |
| Smoke damage in unburned rooms | Not a separate coverage but a frequent argument. Contamination of rooms the flames never reached is direct physical loss, and documentation of extent is what settles it |
Two limits to know before the conversation starts. Whether your contents settle at replacement cost or actual cash value changes the arithmetic completely — see the difference between them. And categories such as jewelry, firearms and cash carry hard sublimits no amount of documentation can lift, listed in what your policy might not cover.
Ask for an Advance
You will need money before the claim is settled: clothes, medication, toiletries, a deposit on somewhere to stay. Insurers can issue advances against contents and against additional living expenses, and they generally do so on request rather than on their own initiative.
Ask in writing, on the first or second day, and ask for both separately. Keep every receipt from the moment you leave the house, including meals, because the standard for additional living expenses is the increase over your normal spending, not the total. Where a state or federal disaster declaration is involved, additional statutory entitlements may apply — that is covered in your rights during a major insurance emergency.
Signing Things Under Stress
Contractors arrive at fire scenes quickly, sometimes before the fire service has left. Some are excellent. The paperwork is where the risk sits.
An open-ended work authorization commits you to pay whatever the contractor bills, which may exceed what the insurer approves. Ask for the scope and price to be tied to the insurer's approved estimate, and get that in writing.
A direction to pay sends the insurer's payment straight to the contractor. Reasonable in itself, but read what it says about disputes and about the balance if the estimate rises.
An assignment of benefits transfers your claim rights to the contractor, who then deals with the insurer directly and can litigate in your name. Several states have restricted these after widespread abuse. Do not sign one at a fire scene.
For the restoration work itself, look for IICRC certification, which is a verifiable credential for restoration technicians, and ask for references from insurers rather than from homeowners.
Air, Odor and Health
Burnt plastics and electronics produce toxic combustion byproducts, and these settle throughout a property rather than staying where the fire was. Respiratory symptoms after re-entering a fire-damaged home are common and are not imaginary.
Do not attempt cleanup without appropriate respiratory protection, and keep children, older adults and anyone with a respiratory condition out entirely until remediation is finished.
A specific safety point on odor treatment. Ozone generators are sometimes proposed for smoke odor. Ozone is a lung irritant, and the Environmental Protection Agency advises against using ozone-generating devices in occupied spaces. If a contractor proposes ozone treatment, the property must be vacated and properly aired before anyone returns, and they should say so without being asked.
Odor also returns. Smoke residue held in porous materials releases again in warm or humid weather, which is why sealing surfaces before repainting is standard practice rather than an upsell. If the smell comes back in the first summer after the rebuild, that is a claim issue worth raising rather than a defect you have to live with.
What People Ask in the First Week
Is the food safe?
No. Heat can compromise sealed containers, and smoke penetrates packaging. Discard it, and photograph what you discard, because food loss is claimable.
Can I wash smoke-damaged clothes at home?
Ordinary detergents do not break down the oily component of smoke residue, and repeated home washing tends to set the odor. Textiles are normally handled as part of the packout by specialist cleaners.
Should I move furniture out myself?
Generally no. Moving soot-covered items spreads contamination into wherever you are staying, which creates a second problem the policy did not anticipate.
How long will this take?
Longer than the estimate. Drying, remediation, adjusting, permitting and rebuilding run sequentially, and much of the delay is structural rather than anyone's fault — see why claims get delayed.
What if the estimate is well below the contractor's?
Compare them line by line first, since omissions are usually specific and demonstrable. If the gap persists, most policies contain an appraisal clause for disputes about amount. If the response is a refusal rather than a low figure, that is a different route — see handling a denied claim.
What if I cannot find the documents I need?
Birth certificates, deeds, titles and policy documents can all be replaced, and doing so early avoids delays later. This is also the argument for keeping copies somewhere other than the house — see keeping documents safe.
The Short Version
Preserve whatever started the fire. If a defective product caused it, your insurer can recover from the manufacturer and your deductible usually comes back with it, but only if the object survives the cleanup.
Secure the building and report the claim on the first day. The duty to prevent further damage is a policy condition, and failing it turns covered damage into an argument.
Treat the packout as the drafting of your contents claim, because that is what it is. Review the inventory while it is being made, keep your own copy, ask who decides what is salvageable, and find out whether storage charges come out of your contents limit or your living expenses.
Ask for advances on both contents and living expenses in writing, keep every receipt from the moment you leave, and check specifically for ordinance or law coverage, which is the most commonly missed item on a fire rebuild.
And be careful what you sign in the first 48 hours, particularly anything assigning your claim to a contractor.
Sources and Editorial Note
Annual figures for home structure fires, casualties and causes are published by the National Fire Protection Association and revised each year. Guidance on ozone-generating air cleaners, including the advice against use in occupied spaces, comes from the US Environmental Protection Agency.
Claims that professional mitigation within a set number of hours reduces restoration costs by a specific percentage circulate widely in restoration industry marketing and are not traceable to published research; they are omitted here rather than repeated. The underlying mechanisms — acidic soot residue, retained firefighting water and smoke migration into unaffected areas — are well established independently of those figures.
Coverage limits and sublimits, debris removal allowances, fire department service charge coverage, ordinance or law availability, appraisal provisions, restrictions on assignment of benefits and subrogation practice all vary by policy and by state. This article is general information about insurance, not legal advice and not advice on your specific policy; confirm every point against your declarations page and endorsements, and contact your state insurance department with questions or complaints.
It is not medical advice either. Exposure to combustion byproducts can cause real symptoms, and anyone experiencing breathing difficulty, persistent cough or irritation after a fire should see a clinician rather than wait for the smell to clear.