The First Hour Decides the Next Six Months
A collision is two events at once. There is the physical one, which is over in a second, and the administrative one, which begins immediately and can run for a year. Almost everything that determines the outcome of the second event happens in the first hour of the first one — before you have calmed down, and while you are least equipped to think clearly.
This guide is about that hour, and about the six decisions after it that most often cost people money.
What Is Actually at Stake
Numbers get thrown around loosely in this subject, and they measure very different things. Here is what the main figures mean.
| Figure | Amount | What it actually measures |
|---|---|---|
| Average collision claim | $5,992 | What insurers pay out per collision claim (ISO/Verisk) |
| Average bodily injury liability claim | $24,211 | Per-claim payout for injury liability — roughly four times the collision figure |
| Total US motor vehicle injury cost, 2024 | $559.3 billion | National Safety Council estimate: medical, wage loss, property damage, administration |
| Medically consulted injuries, 2024 | 4.9 million | People who saw a medical professional after a crash (NSC) |
The gap between the collision figure and the injury figure is the whole point. Property damage is bounded by the value of a car. Injury exposure is not, which is why the paperwork around a sore neck matters more than the paperwork around a dented bumper — and why insurers scrutinise it harder.
The First 60 Minutes
In order:
- Safety first. Hazard lights on. Move vehicles out of traffic only if they are drivable and it is safe. Do not stand between cars or in a live lane.
- Call 911, even for minor damage. An officer's report is a neutral third-party record. Without it, a disputed claim becomes your account against theirs, and adjusters resolve those by splitting fault or denying both.
- Say as little as possible about fault. More on this below. Exchange information; do not narrate the crash.
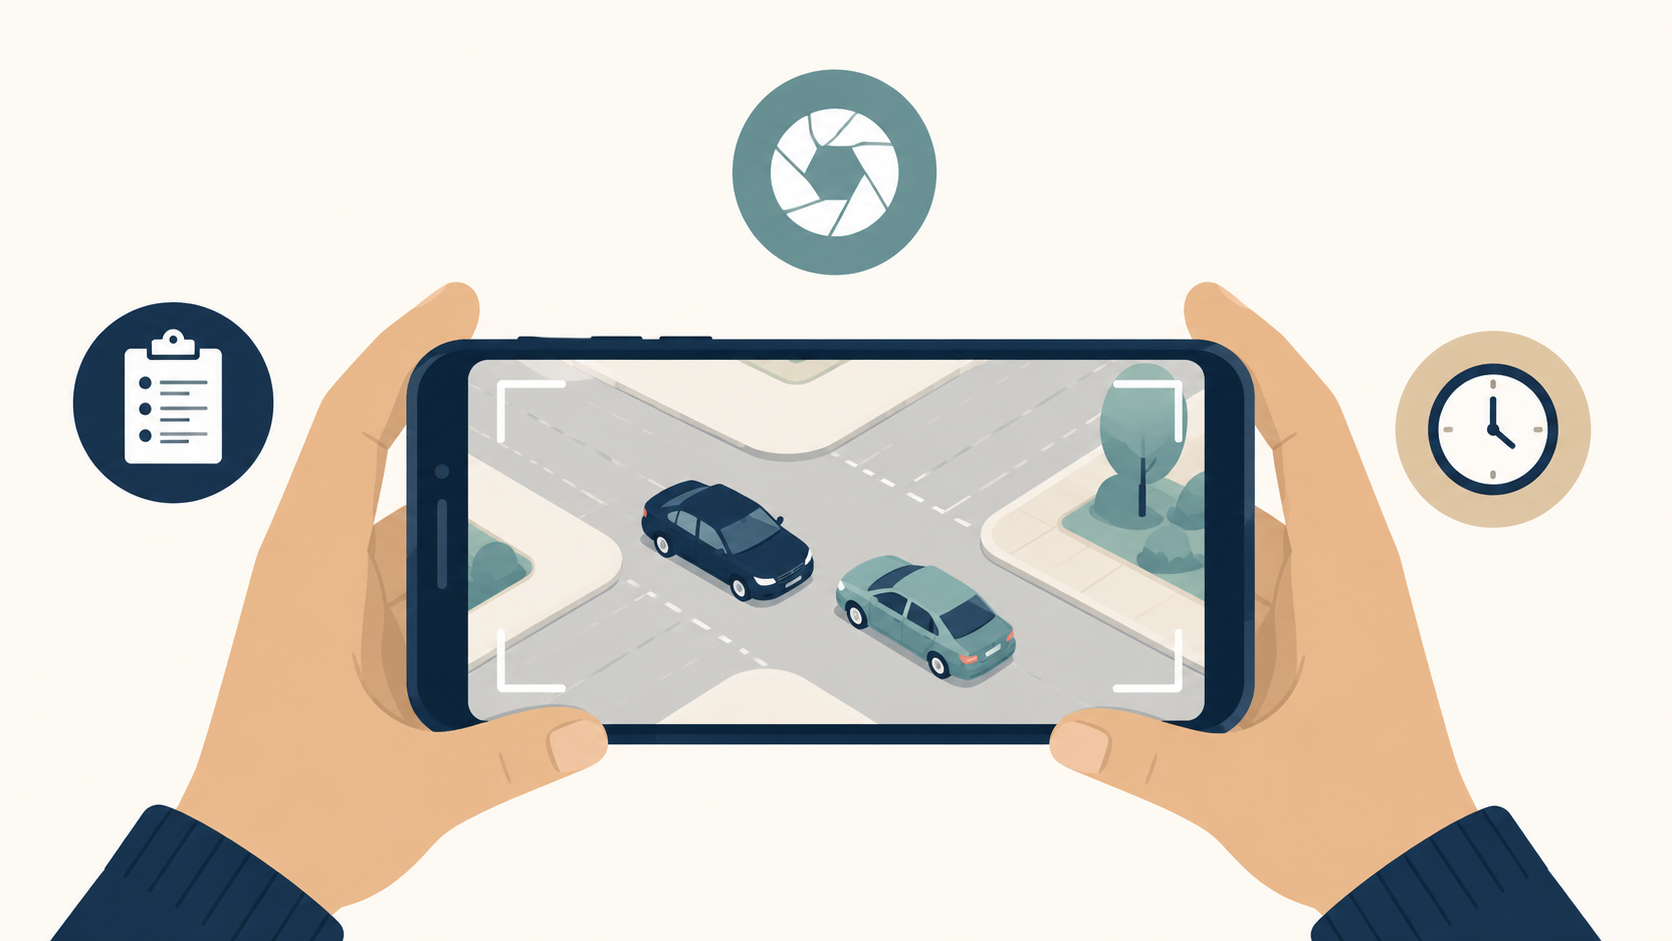
- Photograph before anything moves, if it is safe to do so.
- Get witness names and phone numbers. This is the single most commonly skipped step and the hardest to recover later. Witnesses leave within minutes.
- Note the officer's name, badge number and the report number.
- Notify your own insurer the same day, even if you are not at fault and even if you do not intend to claim.
Five Sentences That Cost People Money
"I'm fine." Adrenaline suppresses pain. Whiplash and soft-tissue injuries commonly present 48 to 72 hours later. A statement recorded at the scene that you were uninjured is used months afterwards to argue that whatever you are treating came from something else. Say that you are not sure and will be evaluated.
"I'm sorry." A social reflex that reads as an admission in a claim file. Check on the other person's wellbeing without characterising the cause.
"Yes, I can give a recorded statement." You are generally obliged to cooperate with your own insurer. You are not obliged to give a recorded statement to the other driver's insurer. Their adjuster is not neutral. Decline politely and refer them to your carrier.
"It's only a scratch, let's not involve insurance." Damage that looks cosmetic is routinely four figures once a bumper sensor or a radar module is involved, and the other driver can report an injury weeks later regardless of what you agreed at the roadside.
Anything posted publicly. Adjusters do look at social media. A photograph of you at a party three days after the crash gets used as evidence about the severity of an injury, out of context and without explanation.
Where You Live Changes the Rules Entirely
This is the part most guides skip, and it can be the difference between full recovery and nothing at all.
Contributory negligence states. In Alabama, Maryland, North Carolina, Virginia and the District of Columbia, being even 1% at fault bars recovery completely. Not reduced — barred. In these jurisdictions, an off-hand apology at the scene is not a minor error.
Modified comparative negligence. Roughly 33 states bar recovery once your share of fault crosses a threshold, either 50% or 51%. Below it, your award is reduced by your percentage. Florida moved into this group on 24 March 2023 under HB 837, ending fifty years of pure comparative negligence. Louisiana followed on 1 January 2026. In these states the entire case can turn on whether an adjuster puts your share at 50% or 51%.
Pure comparative negligence. About a dozen states, including California, New York and Alaska, allow recovery no matter how much fault you carry — reduced accordingly.
No-fault is not what it sounds like. In no-fault states such as New York and Florida, each driver's own Personal Injury Protection covers their medical costs regardless of blame. Fault is still determined for vehicle damage, and the negligent party's insurer still pays for it.
Rules change — Florida and Louisiana both moved recently — so verify your state's current position rather than relying on an article, this one included. Your state insurance department is the starting point.
The Reporting Deadline Nobody Mentions
Several states require a report to the motor vehicle agency that is entirely separate from the police report and the insurance claim. Missing it can suspend your licence even when you did nothing wrong.
California is the clearest example. Under Vehicle Code § 16000 you must file form SR-1 with the DMV within 10 days if anyone was injured or killed, or if property damage to any one person exceeded $1,000. The threshold has not moved since 2017 and is now trivially low — at current parts and labour rates, almost any body shop visit clears it. A police report at the scene does not reliably satisfy the requirement, and the obligation applies regardless of fault. Details are on the California DMV accident reporting page.
Other states have their own thresholds and windows. Check yours in the first day or two, while there is still time.
Documenting the Scene
Adjusters estimate repairs and value using systems like CCC and Mitchell. Sparse documentation does not produce a neutral result; it produces a low one, because the software has nothing to push against.
Photograph more than the damage:
- All four corners of both vehicles, wide enough to show their positions relative to each other and to the road
- Skid marks, debris fields and fluid trails
- Traffic signals, stop signs, lane markings and any obstructed sightlines
- Weather, road surface and lighting conditions
- The other driver's licence, insurance card and licence plate — photograph them rather than transcribing
- The other vehicle's VIN, usually visible through the windscreen at the base
- Visible injuries, then again at 24 and 72 hours as bruising develops
Use your phone's built-in document scanner for the licence and insurance card rather than a third-party app — you are handling someone's identity documents, and there is no reason to route them through an unnecessary service.
Video is better than stills for the overall scene. Walk a slow circle narrating only observable facts: the date, the location, the weather, what you can see. No speculation about cause.
Dashcam and telematics. If you have a dashcam, preserve the file immediately — most units loop and overwrite within hours. If you are enrolled in a telematics program, that data records your speed and braking and can corroborate your account, though be aware it works in both directions. Our guide on claim documentation and evidence collection goes deeper on preserving this material.
The Medical Record Is a Financial Document
Get evaluated within 24 hours, even if you feel fine. This creates a contemporaneous record dated to the crash. Wait five days and the insurer will argue a "gap in treatment" — that something in those five days caused the pain, not the collision. It is one of the most effective and most routine denial arguments there is.
Tell the clinician everything, including symptoms that seem trivial. Anything absent from that first record is difficult to add credibly later. Then follow the treatment plan; missed appointments are read as evidence that the injury resolved.
Keep every bill, referral and receipt in one place. If a bill arrives that looks wrong or wildly out of proportion, read what to do if you receive a massive medical bill before paying it.
The Money: Total Loss, ACV and Diminished Value
If the car is totalled
Insurers pay Actual Cash Value — what your car was worth the moment before impact — not what a replacement costs today. The first offer is a starting position, and the valuation report behind it frequently contains errors.
Ask for the full market valuation report. Check that the comparable vehicles actually match yours on mileage, trim and options, and that the condition rating is not arbitrarily low. Pull your own comparables from listings in your ZIP code. Receipts for recent tyres, a timing belt or major service within the last year can be argued into the value. Our full walkthrough is at what to do if your car is totaled.
Diminished value — read the state rules first
A repaired car with an accident on its history report sells for less than one without. That loss is real and often uncompensated. But eligibility depends heavily on who you are claiming from:
Third-party claims — against the at-fault driver's liability insurer — are recognised in nearly every state as part of restoring you to your pre-loss position. This is the normal route.
First-party claims — against your own collision coverage — are a different matter. Georgia is the one state where this right is clearly established, following State Farm v. Mabry (2001), which required insurers to evaluate diminished value on qualifying claims. A handful of other states have arguable case law. In most of the country, if the accident was your fault, you absorb the loss. Note also that many insurers added explicit diminished-value exclusions to their policy forms after Mabry, so the policy wording matters as much as the state.
Where a claim is viable and the vehicle is late-model, an independent appraisal is usually what makes it stick. Settlements commonly land somewhere between 10% and 25% of pre-accident market value.
Getting your deductible back
If your own insurer pays for repairs while fault is still being sorted out, they will pursue the other carrier to recover what they spent. That process is subrogation, and your deductible should ride along with it. Ask explicitly whether they are pursuing deductible recovery on your behalf, and follow up — otherwise several hundred dollars can sit outstanding for months. Background on how the deductible works is in what a deductible really means on auto insurance.
Two Situations Worth Understanding
The diminished value claim that worked — and why
A driver in Atlanta was rear-ended in a late-model EV. Repairs came to roughly $12,000, paid in full by the at-fault driver's insurer. The car was structurally fine, but the accident was now on its history report and its trade-in value had dropped.
An independent appraisal supported a diminished value claim against the at-fault carrier, and the owner recovered several thousand dollars beyond the repair cost.
The detail that matters: this was Georgia, and it was a third-party claim. The same facts in a state without established diminished value practice, or against the driver's own insurer, would likely have produced nothing. Geography did as much work here as the appraisal did.
The staged accident
A commuter was cut off and then hard-braked into — a manoeuvre designed to produce a rear-end collision, where the following driver is presumed at fault. The other party claimed injury.
A dual-channel dashcam recorded the swerve and the brake with no obstacle ahead. The insurer's fraud unit reviewed the footage and denied the claim.
Without that footage, the presumption in a rear-end collision would have applied, and the outcome would have been an at-fault claim and a multi-year surcharge — see why your insurance premium increased after a claim for what that costs over time.
Both are composite illustrations of common patterns, not accounts of specific individuals.
Post-Accident Checklist
| When | Action | Why it matters |
|---|---|---|
| At the scene | Call police, get report number | Creates a neutral third-party record |
| At the scene | Photograph vehicles, context, documents | Conditions cannot be reconstructed later |
| At the scene | Collect witness contacts | Witnesses disperse within minutes |
| Same day | Notify your insurer | Late notice is grounds for denial |
| Same day | Save dashcam footage off the device | Loop recording overwrites within hours |
| Within 24 hours | Medical evaluation | Closes the "gap in treatment" argument |
| Within days | File any required state DMV report | Missing it can suspend your licence |
| Ongoing | Ask about rental / loss of use coverage | Frequently available, rarely offered unprompted |
| Before signing | Confirm treatment is complete | A release closes the claim permanently |
The Settlement Trap
A quick settlement offer often arrives within days: a modest cheque, framed as getting this dealt with promptly. Signing the accompanying general release closes the claim permanently. If a soft-tissue injury turns out to need three months of physiotherapy, that is now your cost.
Do not sign a final release until treatment has concluded and you know the full extent of what you are settling. Property damage and injury are usually settled separately — you can resolve the car without touching the injury claim, and you should.
Related situations have their own procedures: a hit and run, an uninsured driver, and understanding your own liability limits before you need them.
Frequently Asked Questions
How long do I have to file a claim?
Two separate clocks. Your policy requires prompt notice — usually interpreted as days, not weeks — and late notice alone can support a denial. Your state's statute of limitations for a lawsuit is much longer, commonly two to four years for property damage and injury, and varies by state and claim type. Do not confuse the two.
Should I claim on my own policy if the crash was not my fault?
Often yes, particularly if the other driver is uncooperative, disputes fault or is underinsured. Your insurer repairs the car under your collision coverage and then recovers from the other carrier. It is usually faster, and it puts your own company's resources behind you. You pay the deductible up front and should get it back through subrogation.
What if the police report is wrong?
Factual errors — a wrong plate, an incorrect date — are usually corrected by contacting the reporting officer. Disputed conclusions about fault are much harder to change. In most jurisdictions you can file a supplemental statement to be attached to the report, which does not overwrite the officer's assessment but does put your account on the record.
Am I required to talk to the other driver's insurer?
No. You must cooperate with your own insurer under your policy. You have no such obligation to the other carrier, and no obligation to give them a recorded statement. Referring them to your own adjuster is a normal and reasonable response.
Can I choose my own repair shop?
In most states, yes. Insurers may steer you toward network shops, and those are often perfectly good, but the choice is generally yours. Ask specifically whether the estimate uses OEM or aftermarket parts, since that affects both repair quality and resale value.
Does a no-fault state mean nobody is blamed?
No. No-fault applies to medical coverage: each driver's own PIP pays their medical bills regardless of who caused the crash. Fault is still assigned for vehicle damage, and the at-fault driver's insurer pays for it.
Can I negotiate a total loss valuation?
Yes, and you should. Request the market valuation report, check the comparables against your car's actual mileage, trim and condition, and submit your own listings and maintenance receipts. Valuation reports contain errors often enough that reviewing one is worth the hour.
The Short Version
Three things carry most of the weight. Call the police even when it seems unnecessary. Get evaluated by a doctor within 24 hours even when you feel fine. Say nothing at the scene about who caused what.
Everything after that is documentation and patience. Photograph more than seems reasonable, keep every piece of paper, do not sign a release while you are still being treated, and check your own state's rules — because in five jurisdictions, 1% of the blame means none of the money.
Sources and Editorial Note
Claim severity figures are from ISO, a Verisk business; injury incidence and national cost estimates are from the National Safety Council's Injury Facts. California reporting requirements are from the California DMV. Comparative negligence classifications reflect statutory positions as of mid-2026, including Florida's HB 837 (2023) and Louisiana's change effective 1 January 2026.
This article explains general procedure and is not legal advice. Fault rules, reporting thresholds, statutes of limitation and diminished value rights are state-specific and change. For anything involving significant injury, disputed liability, or a jurisdiction with contributory negligence, consult a licensed attorney in your state.