Health Plan Networks Explained
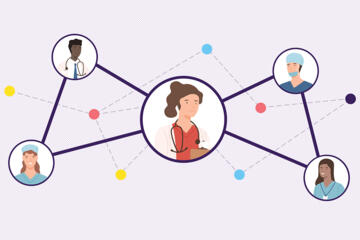
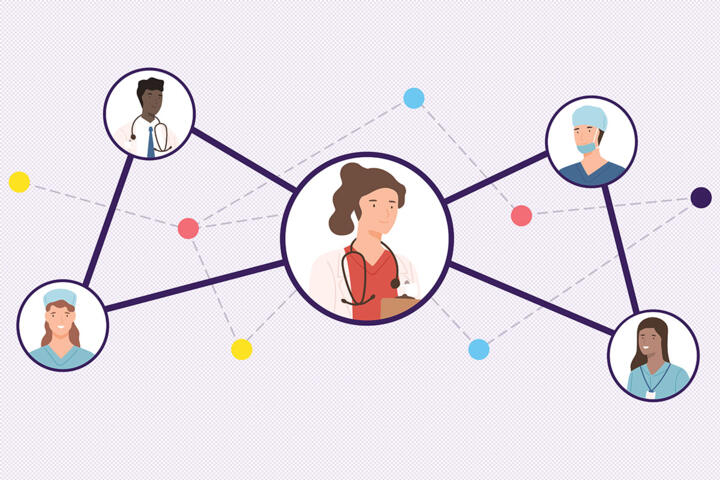
A health plan network is a curated group of healthcare providers, clinics, hospitals, and specialists that an insurer partners with to deliver medical services at negotiated rates. For example, Blue Cross Blue Shield might contract with 50,000 doctors nationwide, creating its network. According to the Kaiser Family Foundation, about 80% of insured Americans have plans that restrict coverage to these networks to some degree. Essentially, the network defines where you can get care with the plan’s preferred pricing.
Networks influence which doctors appear in provider directories, what out-of-pocket costs you face, and whether pre-authorization is needed for services. You might have an in-network primary care doctor but have to pay full retail prices out-of-network. Networks vary widely: some cover a broad swath of providers, others are narrow, focusing on negotiated savings over choice.
When choosing a plan, understanding network size, geographic reach, and provider quality matters. Some plans even list exact negotiated prices per procedure—though you rarely see that publicly. Networks are more than a list; they define the financial framework for your care.
Network Misunderstandings
Many consumers think “network” means every doctor in the area. Not true. Insurers balance cost and accessibility by selectively contracting providers. Some highly rated specialists may be out-of-network, which surprises patients. Plans may label a provider “in-network” due to minimal contracts but with limited appointment availability or outdated contact info.
Out-of-network surprises frequently lead to balance billing, a costly headache where patients pay the difference between insurer reimbursement and provider charges. This is common in emergency situations where choice is limited. People also confuse networks with benefits: having a plan with mental health benefits does not guarantee a choice of in-network therapists.
The consequence? Unexpected bills, delayed care, or forced travel to find network providers. Nearly 30% of ER visits in 2022 involved out-of-network providers, often unintentionally. These misunderstandings drive dissatisfaction and disputes.
Optimize Network Use
Verify Provider Network Status
First, call the provider’s office directly before appointments. Insurer directories are sometimes outdated, sometimes inaccurate. Confirming network status reduces unexpected charges. Tools like the UnitedHealthcare Provider Search or Aetna's online portal refresh data monthly, aiding verification at scale.
Understand Network Types
Choose among HMO, PPO, EPO, or POS plans based on network flexibility. HMOs restrict care strictly to network providers and typically require referrals; PPOs offer partial out-of-network coverage. The more flexible the network, the higher the premiums generally. For example, 2023 average premiums for individual PPO plans were 17% higher than HMOs, per eHealth data.
Use Telehealth Services in Network
Many plans now include telehealth providers in-network, often at no copay. For routine questions, especially with providers like Teladoc or Amwell, this saves money and time. Telehealth penetration among insured Americans jumped to 45% in 2023, per CDC statistics. Quick virtual visits keep you in-network and away from costly urgent care.
Check Negotiated Rates and Pre-Authorizations
Some plans reveal negotiated fees through member portals. Asking your insurer can clarify out-of-pocket costs. Services outside the network often lack these caps. Additionally, understanding which services need pre-authorization, such as MRIs or elective surgeries, prevents denials. This avoids situations where, for example, a $3,000 procedure ends up costing $9,000 out-of-pocket.
Consider Narrow Networks for Cost Savings
Plans with narrow networks deliberately limit providers to cut premiums. While this restricts choice, it can reduce monthly premiums by up to 30% for individuals. Companies like Kaiser Permanente use this model effectively, maintaining high care coordination. Analyze if a narrow network offers trusted providers nearby before enrolling.
Use Employer or Marketplace Tools
Employers and healthcare.gov platforms often provide network comparison tools. Using them reveals if your current specialists appear in the new plan’s network. Jumping into a new plan without this can lead to sudden unavailable providers. Spend 15 minutes in these tools before finalizing coverage; it saves headaches.
Review Plan Updates Annually
Networks change yearly. A provider in-network this year might exit next year due to contract negotiations. Your insurance issuer typically sends these changes in renewal packets or emails. Double-check before renewal to avoid surprises like forced doctor switches mid-treatment.
Document Confirmations
Keep written or emailed proof from providers about network status or coverage. It helps if disputes arise over unexpectedly billed services. Consumers rarely do this but it makes a difference when contesting claims.
Appeal Out-of-Network Claims
If you receive an out-of-network bill despite efforts to stay in-network, appeal with documentation of your attempts. Some insurers have grievance processes reducing bills or reclassifying providers. It does require persistence but can save thousands.
Practical Examples
A mid-sized business shifted its employees from a nationwide PPO to a regional HMO network in 2020. Initially, 35% of employees faced loss of preferred doctors. After negotiating with local providers and updating tools, out-of-network claims dropped 40% the following year, and premiums fell by 22%. The business used a vendor called Castlight Health to analyze provider coverage and employee choices.
Another patient, switching insurance in California in 2023, verified network status using Anthem’s online directory plus phone calls. This avoided choosing a primary care doctor who was actually out-of-network under the new plan. Without this effort, she would have faced $500+ annually in extra copays and fees.
Choosing Plans Checklist
| Criteria | Network Size | Provider Quality | Out-of-Network Cost |
|---|---|---|---|
| HMO | Limited | High | No Coverage |
| PPO | Wide | Wide Range | Partial Coverage |
| EPO | Medium | Moderate | No Coverage |
| POS | Medium | Moderate | Partial Coverage |
Network Mistakes to Skip
Ignoring network verification costs money. Insurers update networks each year, but many rely solely on provider directories instead of direct calls. Doctors switch networks or retire. Not researching this leads to surprise bills. Assuming that coverage means choice undermines savings and care continuity.
Failing to appeal unexpected out-of-network charges often results in paying full billed amounts unnecessarily. Patients should push back with documentation—it works sometimes, but the effort is often skipped.
Lastly, selecting the cheapest premium plan without looking at network size annoys patients with forced long drives or provider shortages. It rarely works out over time.
FAQ
What is the difference between in-network and out-of-network?
In-network providers have contracts with your health plan offering negotiated rates and usually lower copays. Out-of-network providers lack these contracts, so you face higher costs or full charges.
Can I see out-of-network providers?
Yes, but usually at higher cost and with less coverage. Emergency care is a notable exception but can still lead to bills if the facility is out-of-network.
How do I find if my doctor is in the network?
Use your insurer’s online directory and call your doctor’s office to confirm. This two-step check is critical to avoid surprises.
Are specialist visits covered in my plan?
Specialist coverage depends on your plan and network. Some plans require referrals for specialists while others do not. Confirm with both insurer and provider.
Do network providers charge the same everywhere?
No. Negotiated rates vary by geography and insurer. Same specialist could charge differently if contracted with several insurers.
Author's Insight
I've managed healthcare benefits for over a decade, working directly with insurer networks. The complexity is more than jargon; it affects budgets and patient satisfaction daily. From firsthand experience, directly calling providers beats relying on directories, which almost always lag. One medical bill audit saved a client $1,200 by uncovering a hidden out-of-network status. And yet, many give up on appeals. I recommend documenting, questioning, and proactive planning—to dodge these costly pitfalls.
Key Takeaways
Health plan networks are contracts shaping your healthcare costs and options. Avoid surprises by confirming provider network status annually, understanding your plan type, and using available online tools and direct contact. Track network changes and appeal unexpected charges fast. Awareness turns confusing contracts into manageable decisions. The effort? Absolutely pays off in saved dollars and peace of mind.