Why Exams Matter for Policies
Insurance companies require medical exams to assess the risk they take on by insuring an individual. During this exam, trained professionals collect data that directly impacts policy approval and pricing. Commonly, the exam lasts about 30 minutes and may include several tests.
For example, a 2018 study by LIMRA found 76% of life insurance applicants underwent a medical exam before policy issuance. This sets a baseline of health so the insurer can predict life expectancy or health trends.
You might think it’s just a blood test, but it’s more than that. Several measurements add context to your health profile.
Common Misunderstandings
Many applicants wrongly assume the medical exam is a pass/fail test. It isn’t. The results influence premium tiers or coverage restrictions, not automatic acceptance or rejection. Insurers combine exam data with questionnaires and records to form a risk picture.
Missing this nuance can backfire. If you underestimate the exam’s role, you may apply expecting standard rates yet end up with higher premiums or exclusions, complicating your finances over the policy life.
Another mistake is neglecting preparation. Drinking excessive coffee or not fasting can skew blood work results. I witnessed one client’s cholesterol spike due to poor exam prep, increasing premium costs substantially.
Remember, insurance underwriters often look at trends. One abnormal finding can trigger follow-up, delaying policy issuance.
What to Expect During the Exam
Height and weight measurement
This gauges body mass index (BMI), a standard risk indicator. High BMI correlates with increased health risks like diabetes or heart disease. The examiner records these figures to compare with medical histories.
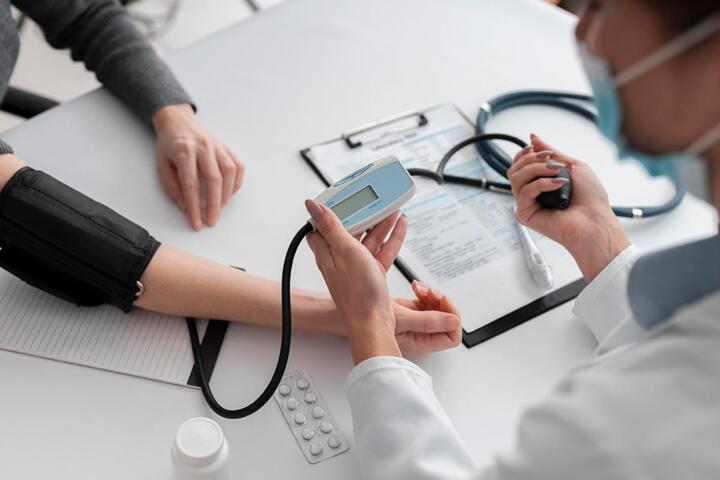
Blood pressure reading
Hypertension is linked to cardiovascular events. Blood pressure outside normal ranges (generally 90/60 mmHg to 120/80 mmHg) flags higher risk. Insurers track this carefully, especially for applicants over 40.
Blood draw for analysis
Common tests include lipid panels, glucose, liver, and kidney functions. For instance, HDL and LDL cholesterol levels influence heart health assessment. A typical blood draw volume is around 10-15 ml. This testing is done by labs or sometimes via point-of-care devices.
Urine test
Urinalysis reveals kidney health and metabolic issues like diabetes. Detecting protein, glucose, or blood informs risk severity. This test is quick and uses a dipstick with color-coded results.
Medical history review
The examiner discusses chronic conditions, medications, and lifestyle habits. Honesty here matters because insurers verify this information against exam findings and databases.
Physical exam
The examiner checks heart, lungs, and overall physical condition. This might seem routine but can catch abnormalities missed in labs. It lasts about 5 minutes and includes listening to heart rhythms.
Additional screenings
Depending on age, policy type, or insurer, extra tests like EKGs or stress tests may apply. These screen for heart irregularities not caught in routine checks. For people over 50, such add-ons are more frequent.
Data use and risk scoring
The collected data feeds into underwriting models. Algorithms combine quantitative results with qualitative factors to assign risk categories—this affects premiums and coverage limits.
Tools and service providers
Companies like Quest Diagnostics or LabCorp often perform testing, following insurer protocols. Some insurers use paramedical nurses who visit your home or workplace, a service gained traction around 2019 to improve convenience.
Real Exam Outcomes
One case involved a 45-year-old male applying for a $500,000 term life policy. His exam revealed untreated hypertension and elevated cholesterol. After medication and lifestyle changes recorded over six months, his premiums dropped 30%. The insurer reclassified him to a better risk tier.
Another example: a woman in her 30s skipped fasting before the exam. Her blood glucose spiked, prompting a diabetes suspicion. This delayed her policy by two months and increased costs, although later cleared. It highlights exam prep matters.
Checklist Before Your Exam
| Step | Action | Impact | Notes |
|---|---|---|---|
| 1 | Fast for 8-12 hours | Accurate blood results | Water allowed |
| 2 | Avoid caffeine | Stable blood pressure | No coffee or tea |
| 3 | List medications | Informs risk analysis | Include dosages |
| 4 | Avoid strenuous exercise | Keeps vital signs normal | Day before exam |
| 5 | Prepare health history | Accurate responses | Review previous records |
Errors to Watch for
Do not exaggerate health status or hide conditions. Insurers use databases like MIB Group to cross-check data—the risk of being caught is high.
Skipping fasting is a repeated error. Results skew, causing unnecessary flags. One client blamed this on a misunderstood email instruction (version 2.1), which, frankly, most people skip.
Failing to disclose medications can classify the applicant into a higher risk pool, driving premiums up.
Also, dismissing the medical exam as insignificant. I've seen multiple cases where a red flag in the exam caused delay or denial—often preventable by early physician consultation.
FAQ
What tests are included in a medical exam?
Tests usually include height, weight, blood pressure, blood and urine analysis, medical history review, and a brief physical exam.
How long do results affect my policy?
Results influence initial underwriting and premiums but generally do not affect coverage during the policy, unless a policy is reinstated or medically reviewed.
Can I prepare for the exam to improve my chances?
Yes. Fasting, avoiding caffeine, listing medications, and managing health conditions beforehand can yield more accurate, favorable results.
Do all insurance policies require a medical exam?
No. Some term life or simplified issue policies waive exams if coverage sought is low, but full underwriting usually needs one.
What happens if my results show a health issue?
Underwriters analyze the risk; rates may increase, exclusions added, or in rare cases, applications denied. Follow-up testing or doctor records may be requested.
Author's Insight
From my years advising on life insurance, medical exams are routinely underestimated by applicants. Preparing properly often cuts wait times and prevents surprises. Accuracy matters—lying or omitting info leads nowhere. I recommend clients review recent labs and consult their doctor to correct any abnormalities well before scheduling exams. It’s not just paperwork; it influences your financial security in unexpected ways.
What to Remember
Medical exams for policies check a range of physical and biochemical indicators to assess risk. Each test plays a role in unlocking access, costs, and coverage terms. Preparing properly, providing honest info, and understanding the scope helps smooth the process. Remember, exam results don’t simply approve or deny but paint the full picture insurers need to price risk fairly and responsibly.